An alpha creation firm.

Our returns come from specific, structural advantages — in situations most capital does not see, and few buyers are equipped to execute. They do not depend on market exposure, cycle timing or sector tailwinds.

The central question
Constrained

01Constrained

Resolved

02Resolved

Recorded

03Recorded

[ GDP — OUR FIRM / Special situations · Alternative assets ]

We are price makers, not risk harvesters

There are two kinds of investment operation. Those that harvest beta — systematic, market-correlated returns. And those that manufacture alpha — asymmetric returns that cannot be explained by exposure to broad market factors.

Risk harvesters buy exposure to risk premiums and collect them over time. Price makers identify situations where the market has systematically mispriced an asset, understand precisely why, and extract that value through access, analysis and operational capability.

Who is on the other side of this trade, and what constraints are they facing? What asymmetries are in our favour that allow us to exploit those constraints?

These are not framing questions. They are the test. A vague answer to either is a valuation disagreement, not a structural opportunity — and valuation disagreements resolve when sentiment changes. Structural constraints do not.

The central question

[ GDP — HOW WE INVEST / Acquisition alpha ]

Our first source of alpha is the acquisition itself.

How we invest

Acquisition alpha

We focus on opportunities where there is a constraint on the seller: pressure that forces a transaction, complexity most capital will not do the work to understand, a profile outside most mandates, a need for discretion, or a clock. The constraint creates an opportunity to lock in alpha at acquisition that can be released once it is resolved.

When we can capture acquisition alpha

Whether we can capture that difference turns on what specific asymmetries we can identify such as information that materially affects the situation, the analytical depth to work through the root problem, the structure to act while others are stalled, and skilled in-house teams that we know can do the work. We move forward only when we can name our asymmetrical advantage(s).

[ GDP — HOW THE GROUP WORKS / The alpha chain ]

Constructing the alpha chain to capture the full return on investment

01.

We begin with the exit in mind

We see considerable distressed and special situation deal flow, and our initial assessment is driven by the ability to articulate a predictable exit.

02.

We underwrite before we commit.

Each situation is written up against the same discipline: what is wrong, what it costs to fix, what it is worth once fixed, and the exact asymmetries we control to capture alpha.

03.

We use our own internal teams

The group's own teams — marketing, technology, construction, restructuring — carry the plan out, so the value the underwriting identified is captured efficiently.

[ GDP — INVESTMENT FOCUS AREAS / Where we invest and operate ]

Where we invest and operate

Investment focus areas

Each focus area is a profile of situation we know deeply, and all four run on the same core capabilities and the same back office, whose cost the group already carries.

001. / Althara

Residential & commercial real estate

Planning and title

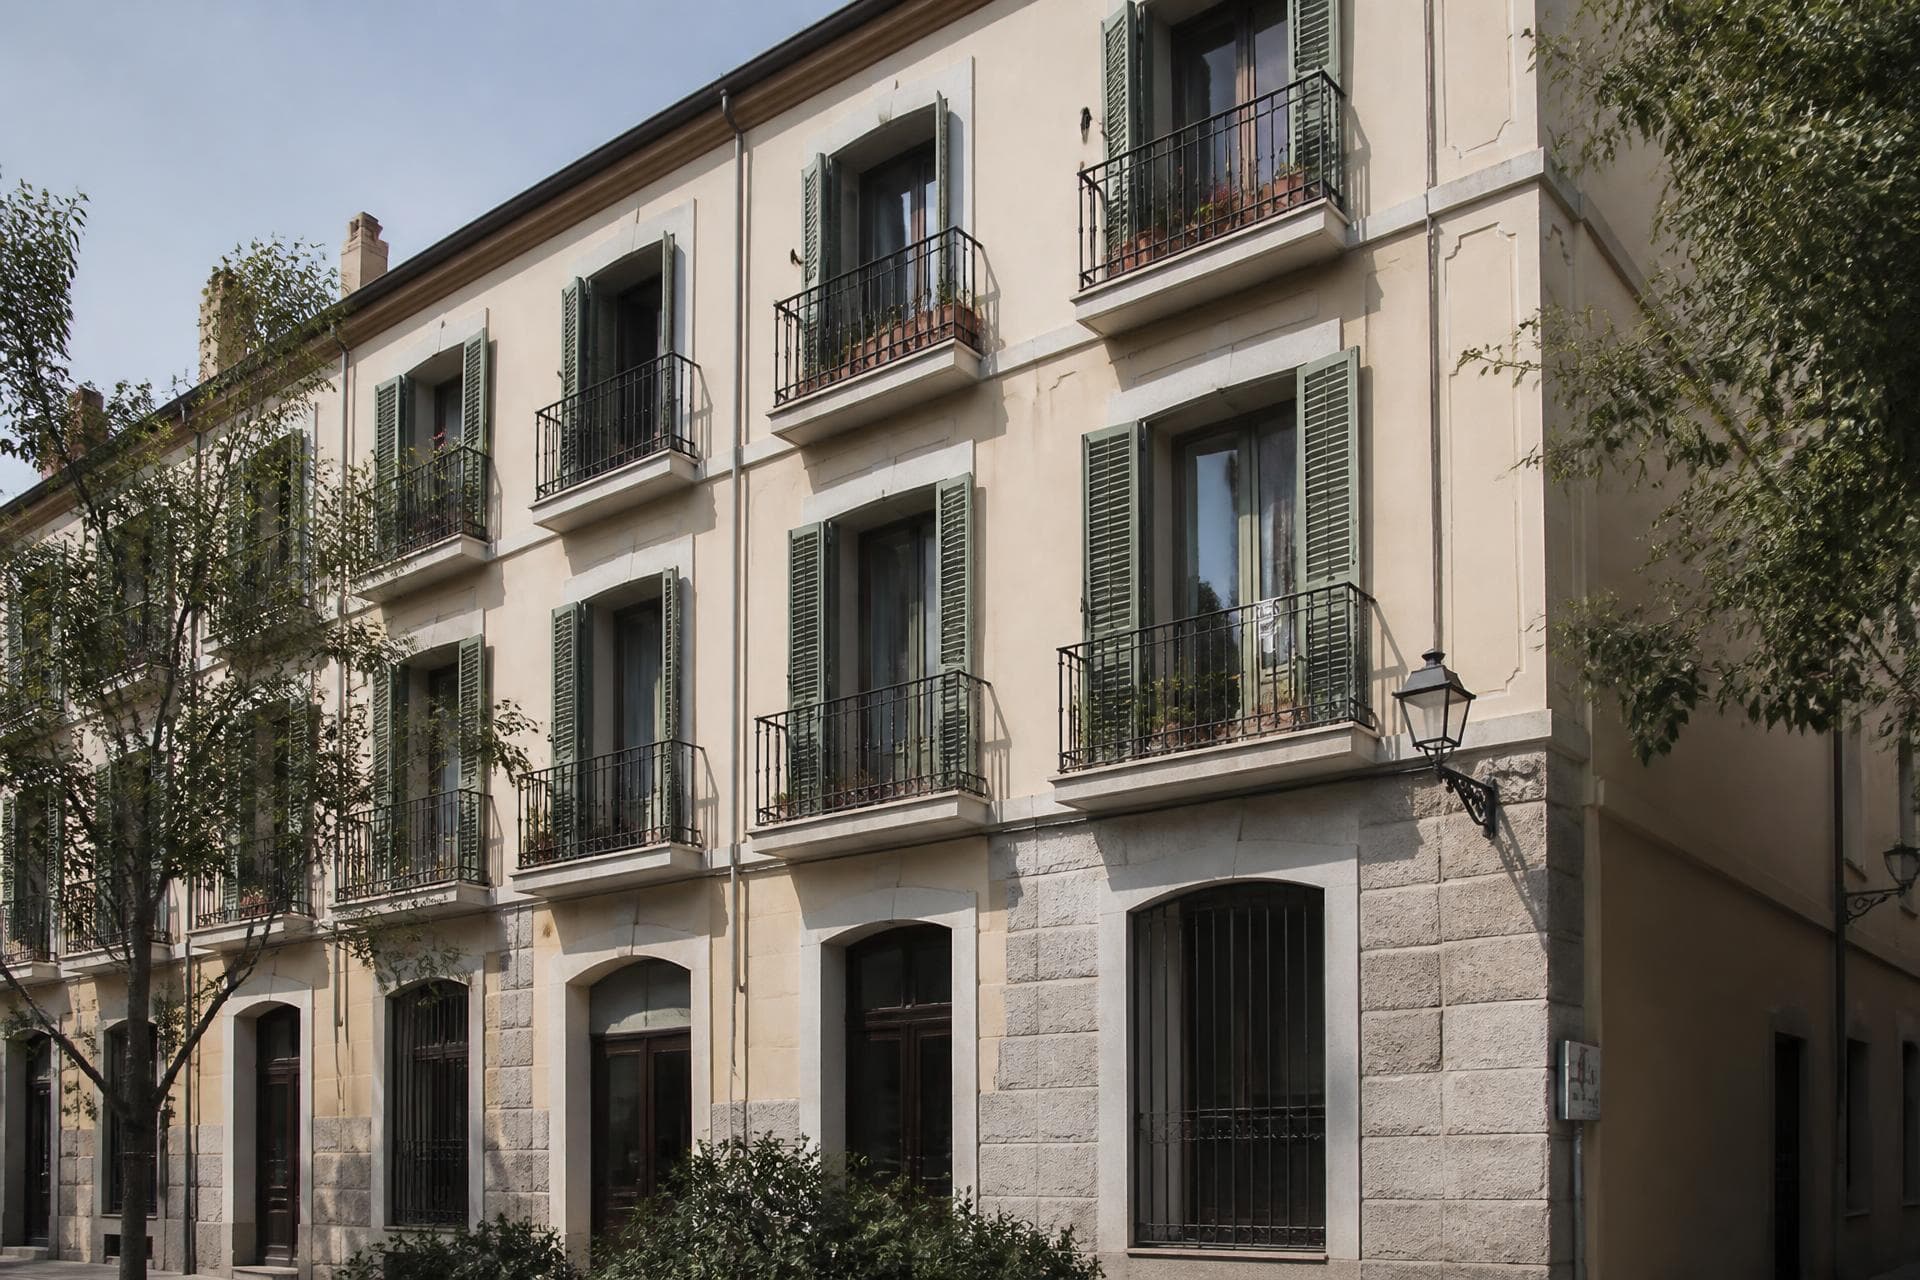
Residential and commercial property where planning, title or occupation is unresolved.

Typically an unissued consent, an unclear title, or unresolved occupation, worked through to a finished, financeable asset.

Planning positionTitle and encumbranceOccupation and possession

002. / Adark

Restaurants & service businesses

Arrears and licensing

Trading businesses constrained by arrears, licensing or cost structures that were left uncontrolled.

Arrears settled and bounded, licences brought into order, the cost base rebuilt, and the business run long enough to show what it trades at.

Arrears and liabilitiesLicensingCost structure and management

003. / Oxono

Digital & AI-enhanced businesses

Ownership and operating model

Platforms with established users and revenue but no strategic ownership, and businesses where technology changes the operating model.

Commercial terms, product quality and accountable ownership put around an audience that already behaves like a business.

Ownership and controlProduct and revenue qualityOperating model

004. / Hospitality coming soon

Hospitality & resorts

Structure and scale

Larger and cross-border situations, frequently beginning with establishing what is genuinely owned and owed.

The first work is factual: corporate structure, liability perimeter, real cash position. A view on value follows.

Corporate structureLiability perimeterScale and cross-border

[ GDP — CRISIS MANAGEMENT ]

Some businesses do not need capital. They need crisis management.

GDP's crisis management division handles crisis and change management for the group's own portfolio and for outside businesses: stabilising the position, establishing the facts, and executing the changes that restore viability — discreetly.

Crisis management
Stabilise, establish the facts, plan and execute the change.

01.Stabilise.

02.Establish the facts.

03.Plan and execute the change.

[ GDP — THE SYSTEM / One discipline, whole book ]

GDP C.A.P.T.U.R.E

How each situation is assessed, underwritten and accounted for — from first sight of a deal to realised return. One discipline, applied to the whole book.

C.A.P.T.U.R.E is GDP's Core Alpha Performance, Transaction Underwriting, Returns Engine.
Inside C.A.P.T.U.R.E
01.CORE ALPHA

Core Alpha Performance

How the group is performing at creating value, measured continuously across the whole portfolio rather than deal by deal.

02.UNDERWRITING

Transaction Underwriting

The full assessment that runs before capital moves: the situation, the plan, the budgets, the risks, and the case for why the group should own the problem.

03.RETURNS

Returns Engine

Where the value stands on every holding: what has been captured, what remains, what it will cost to capture it, and what that implies for hold, accelerate or realise.

THE ALPHA CHAIN VALUATION MODULE

Full Value − Entry Price = Gross Alpha

Remaining Gross Alpha − Cost of Capture = Net Alpha

[ GDP — INVESTORS / Capital allocators ]

We give access to our deal flow to a small number of capital allocators.

We often give access to our deal flow to selected capital allocators. Our approach to sequentially derisking situations along an alpha chain means that allocators can participate at stages that match their mandate.

By the time a situation is presented to an investor within our GDP C.A.P.T.U.R.E system, the underwriting work is done, the constraints are mapped and the alpha chain is built. The return at each stage traces to resolution of the specific constraints resolved.

Investors who want access to situations that they would not ordinarily see and who lack the capacity to transform the asset look to GDP for their strong, pure alpha allocations.

[ GDP — CONTACT US / In confidence ]

If you are a capital allocator, or have a situation you think we should look at...

Contacts

info@gestiondelpapeleo.com

Spain · Balearics · Selective cross-border

I am a (optional)

We read each enquiry and reply directly

Navigation

Enquiries

We create returns from specific, structural advantages in situations few buyers are equipped to underwrite and execute.

Growth Delta PartnersEST. 2021 · LAST UPDATE: Q3 2026Spain · Balearics · Selective cross-border

an alpha creation firm.

2026© Growth Delta Partners · For informational purposes only